US mortgage rate hits 6.95%: $400,000 loan costs $2,648 a month
Freddie Mac's September 17 weekly average rose to 6.95%. Principal and interest on a $400,000, 30-year fixed loan is about $2,648 a month before tax, insurance, points and fees.
Three critical developments
- The 30-year fixed mortgage average rose from 6.76% to 6.95% in one week, while the 15-year average increased from 6.09% to 6.26%.
- On a $400,000, 30-year loan, estimated monthly principal and interest rises from about $2,597 to $2,648.
- The official 10-year Treasury par yield reached 5.01% on September 18; that can pressure mortgage pricing, but the two rates do not move one-for-one or simultaneously.
$400,000 loan comparison over 30 years
The principal and term stay constant so the table isolates the effect of the interest rate.
| Rate | Reference | Monthly payment | Total interest over 30 years |
|---|---|---|---|
| 6.26% | PMMS one year earlier | $2,465.47 | $487,569.53 |
| 6.76% | Previous week | $2,597.05 | $534,938.66 |
| 6.95% | September 17, 2026 | $2,647.79 | $553,204.99 |
Quick answer: What happened to mortgage rates?
Freddie Mac's weekly average, built from thousands of loan applications, put the US 30-year fixed mortgage rate at 6.95% as of September 17, 2026. It was 6.76% a week earlier and 6.26% a year earlier. The same release put the 15-year fixed average at 6.26%, versus 6.09% a week earlier and 5.41% a year earlier.
What does the official series measure?
PMMS is a weekly national average from eligible purchase applications that lenders submit through Freddie Mac's Loan Product Advisor. It is not a same-day quote from one lender. Credit score, debt-to-income ratio, down payment, location and product terms can change a personal offer. Freddie Mac no longer publishes average points and fees, so the 6.95% rate is not the complete cost of credit.
How much does the weekly move add to a $400,000 loan?
Assuming $400,000 of principal, a 30-year term and a fixed rate, monthly principal and interest is $2,597.05 at 6.76% and $2,647.79 at 6.95%. The weekly rate change adds about $50.74 a month and roughly $18,266 of nominal interest across 360 payments. The illustration assumes no refinancing, prepayment or additional charges.
Sensitivity per $100,000 borrowed
Under the same formula, a $100,000, 30-year loan carries monthly principal and interest of $661.95 at 6.95%. The payment is $649.26 at the previous week's 6.76%, a difference of $12.69. This scales linearly with principal, but an actual APR, points and fees do not have to scale the same way.
Why watch the 10-year Treasury yield?
The US Treasury's official curve shows the 10-year par yield rising from 4.94% on September 17 to 5.01% on September 18. Long-term mortgages price comparable risk-free yields plus prepayment, duration, credit and intermediation risks. The 10-year yield is therefore an important reference, but it does not imply an identical same-day move in the mortgage rate.
Did the Fed hike directly set the mortgage rate?
The Fed raised its target range by 25 basis points to 3.75%–4.00% on September 16. That decision has a direct channel into short-term rates, while a 30-year mortgage also prices future inflation, growth, Treasury supply, demand for mortgage securities and credit spreads. Attributing the weekly PMMS move to the Fed alone would claim more causality than the data support; the signals need to be read together.
What does this mean for my money, business or portfolio?
A homebuyer should compare APR, points, fees, tax, insurance and total cash required—not only the headline rate. Higher financing costs can pressure affordability and sales velocity for homebuilders and property businesses, while bank application volumes and lending margins may move differently. For a portfolio, a 10-year yield near 5% can raise discount rates, but it does not guarantee a direction for housing shares, banks or REITs. This is not investment advice.
Method and limitations
The monthly payment uses P×r×(1+r)^360 / ((1+r)^360−1), where r is the annual nominal rate divided by 12. Dollar values are rounded to cents. PMMS is a national average, not a personal quote. As the CFPB advises, borrowers should compare loan size, rate, points, closing costs, APR, term and adjustable-rate risk together.
 CONSUMER FINANCE · AUTOMATIC REFUND
 HOUSING · TURKSTAT DATA ANALYSIS
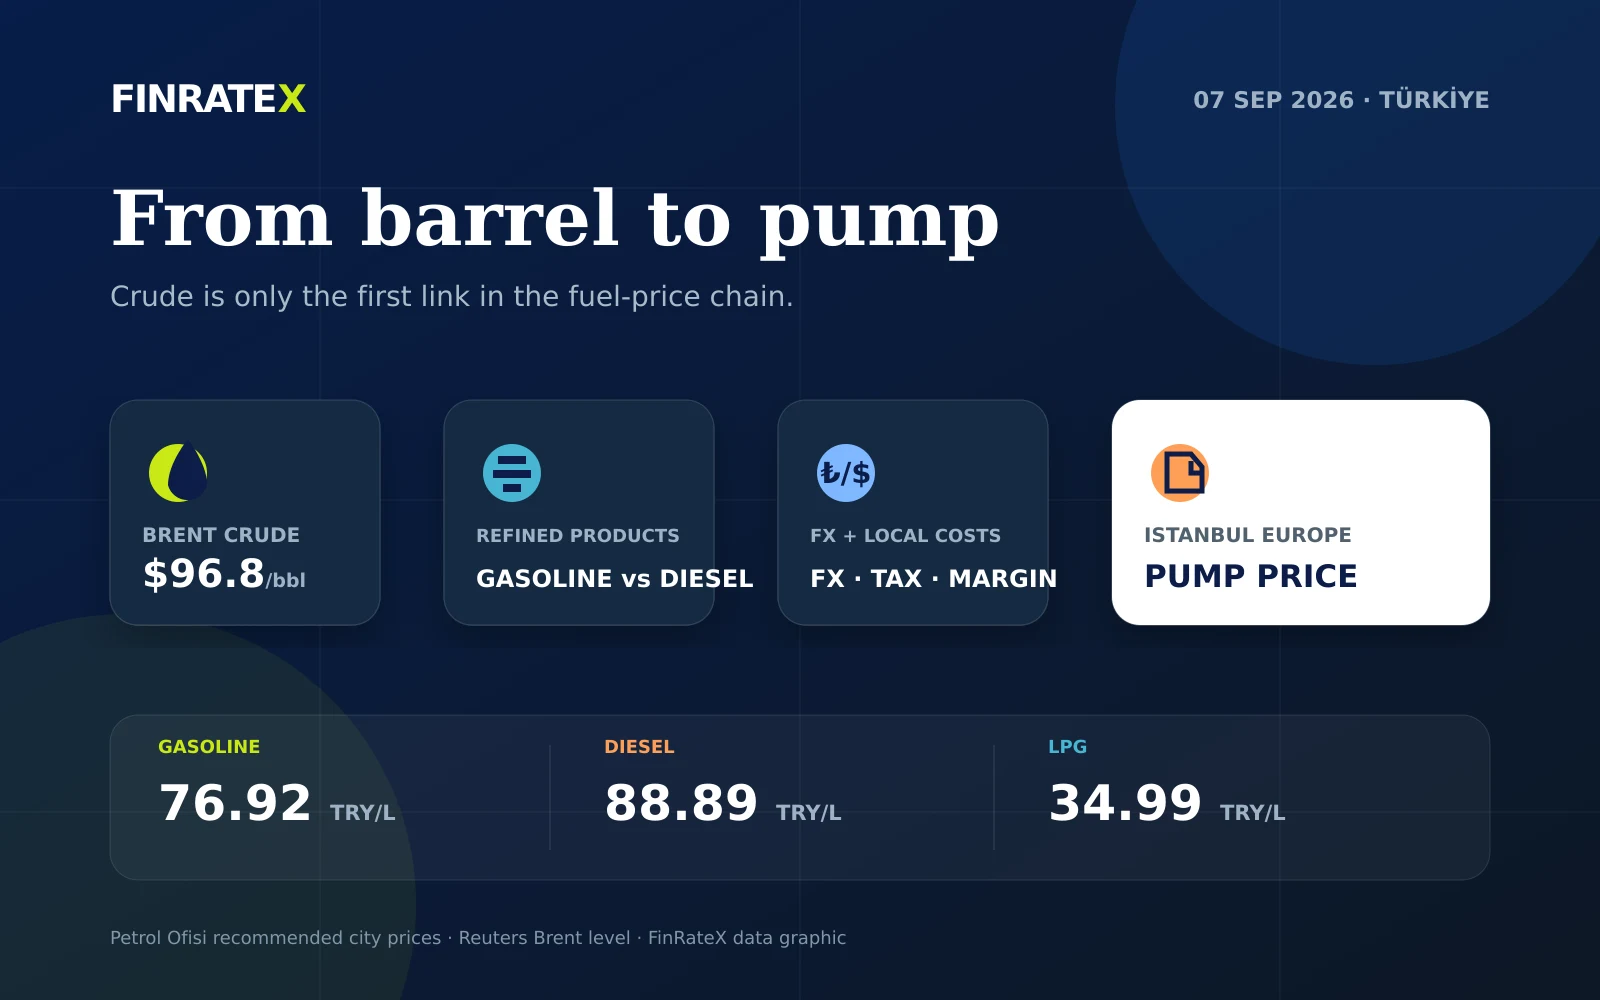 AUTOMOTIVE · TURKSTAT DATA ANALYSIS