Why can gold investors lose money while gold is rising?
A higher screen price does not mean the amount an investor can cash out has risen by the same measure. The spread, trading frequency and purchasing power must be read together.
In this article
The price shown for gram gold and the amount that reaches an investor’s account answer different questions. A reference price indicates market direction; the net outcome depends on the quantity purchased, the institution’s repurchase quote and any additional costs. The distinction is most visible over short holding periods.
MetalKur’s spread and break-even analysis shows that, on a TRY 100,000 budget, a hypothetical spread equal to 2% of the asking price reduces immediate cash-out proceeds to TRY 98,000. The institution’s bid would then need to rise by about 2.04% for those proceeds to return to the starting amount. The 2% example is not a market average or a current bank measurement.
The gap between a 2% loss and a 2.04% recovery comes from different bases. The loss is measured against TRY 100,000, while the required increase starts from TRY 98,000. The necessary move is in the institution’s bid; an equal rise in the international gold price alone does not guarantee the same outcome.
Do not collapse three different calculations into one
- The reference price describes market direction; the institution’s bid determines what the investor can cash out at that moment.
- Recovering a percentage loss requires a larger percentage gain because the gain starts from a smaller remaining amount.
- Nominal break-even does not restore purchasing power unless inflation and alternative returns over the same period are also considered.
Costs compound as the number of trades rises
FinRateX’s added scenario assumes an unchanged market price, a spread equal to 2% of the asking price on every completed buy-sell round trip, fractional gram trading and full reinvestment of proceeds. The remaining amount is TRY 100,000 × 0.98ⁿ; additional fees are excluded.
| Completed buy-sell round trips | Amount remaining | Loss from starting amount |
|---|---|---|
| 1 | TRY 98,000.00 | TRY 2,000.00 |
| 3 | TRY 94,119.20 | TRY 5,880.80 |
| 5 | TRY 90,392.08 | TRY 9,607.92 |
What does the repeated-trading table show?
With the market price fixed, 98% of capital remains after each round trip. One round leaves TRY 98,000, three leave TRY 94,119.20 and five leave TRY 90,392.08. Real price changes can create gains or additional losses, and an institution’s spread can narrow or widen. The table shows only that frequent trading is not cost-free.
RESEARCH · The safe-haven label does not remove transaction losses
Baur and Lucey’s 2010 study reports that gold can hedge equities on average and act as a safe haven in some extreme equity-market conditions in the United States, United Kingdom and Germany, while the safe-haven effect can be short-lived. That scope is not a measure of a Turkish retail gram-gold trade after the spread. FinRateX’s interpretation is that studying portfolio relationships and calculating the net profit on a particular transaction are different exercises.
REAL RETURN · Nominal break-even is not purchasing-power break-even
Even after the spread is recovered, the general price level may have risen. If nominal net return is r and period inflation is π, real return is (1+r)/(1+π)−1. Erb and Harvey’s The Golden Dilemma critically examines the narrative that gold is an inflation hedge. Its historical assessment should not be converted into a forecast for today’s price.
CHECKLIST · Put three numbers side by side before trading
Using quotes for the same product at nearly the same time, compare the total purchase amount, immediate cash-out proceeds and any additional costs. Purity, packaging, unit constraints and repurchase terms can change the outcome for physical products. Looking only at the ask hides those differences. The most useful check is: “If I buy now and immediately sell under the same conditions, how much reaches my account?”
Calculation notes
The MetalKur source calculation and FinRateX’s repeated-trading scenario are shown separately. Every scenario figure is hypothetical; the analysis contains no bank-price survey, current average spread or forecast of how long a return would take. Publisher abstracts were used for the academic sources. The MetalKur article and DOI records were checked on October 5, 2026. Citing MetalKur as a source does not imply independent institutional endorsement. This material is for information and is not personal investment advice.
 GOLD · CURRENT PRICE GUIDE
 US ECONOMY · EMPLOYMENT
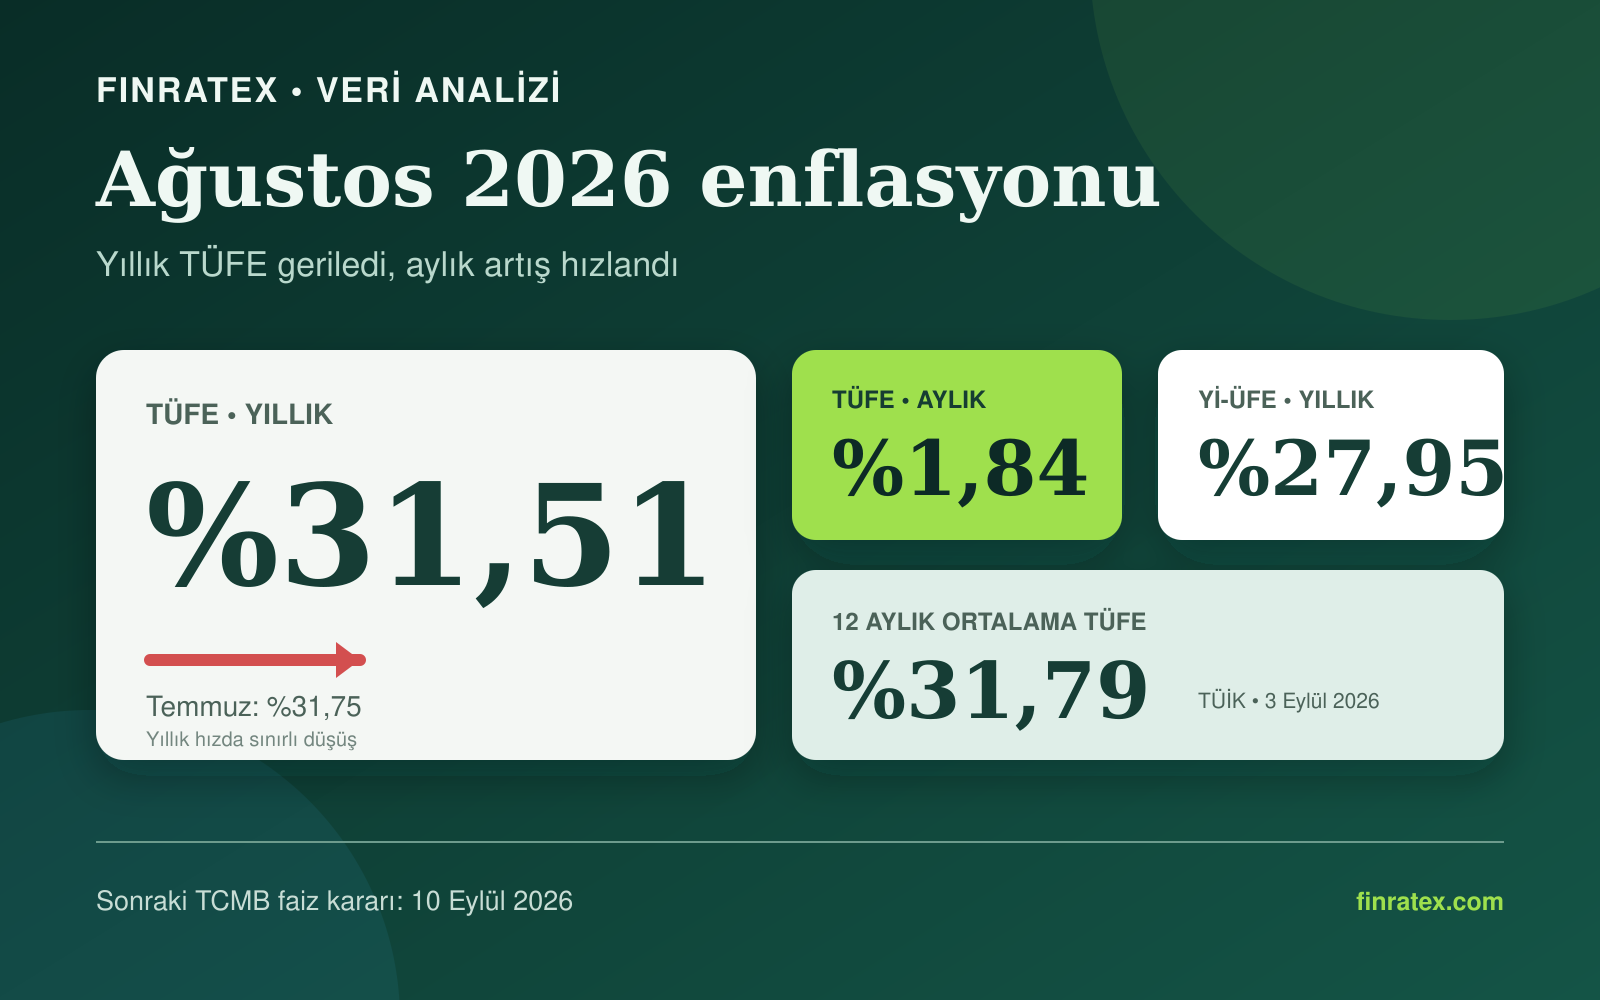 TÜRKİYE ECONOMY · INFLATION