Togg’s zero-interest loan: why TRY 1 million means TRY 166,667 a month
Togg’s TRY 1 million zero-interest T10F V2 loan is repaid in six months. We compare the TRY 166,667 payment with smaller loans and upfront cash needs.
In this article
In Togg’s personal financing options, zero interest comes with repayment of the principal over a short period. Choosing the largest zero-interest T10F V2 loan reduces the cash contribution on day one while increasing payments over the following six months.
This article explains the relationship between loan size, term and upfront cash. Banks’ interest-free cash advance campaigns are a separate product, with card limits and different access conditions.
Three distinctions that change the budget
- The interest rate does not describe repayment speed: dividing the same principal by fewer months raises the monthly burden.
- A lower installment may also mean a smaller loan. Options are not equivalent until the upfront cash difference is included.
- The loan amount is not the car’s price. Insurance, any loan fees and running costs need their own budget.
T10F and T10X V2: zero-interest options
Personal-customer table · October 6, 2026. Payments are Togg’s published rounded figures, not vehicle sale prices.
| Version | Loan | Term | Monthly payment |
|---|---|---|---|
| T10F V2 | TRY 1,000,000 | 6 months | TRY 166,667 |
| T10F V2 | TRY 800,000 | 8 months | TRY 100,000 |
| T10F V2 | TRY 600,000 | 12 months | TRY 50,000 |
| T10X V2 | TRY 800,000 | 6 months | TRY 133,333 |
| T10X V2 | TRY 600,000 | 8 months | TRY 75,000 |
| T10X V2 | TRY 400,000 | 12 months | TRY 33,333 |
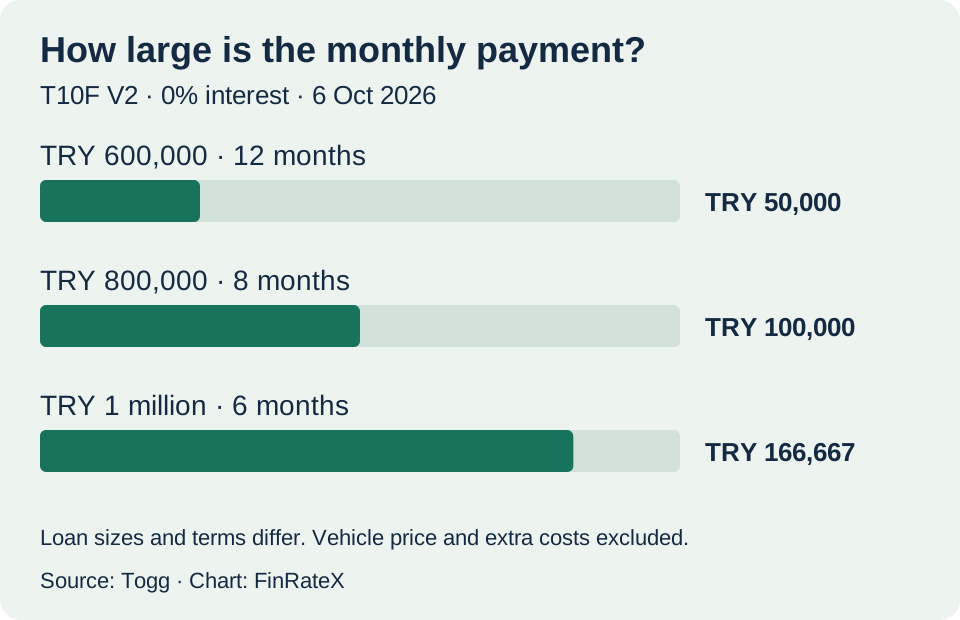
The six-month calculation for TRY 1 million
In a simple zero-interest schedule with equal principal payments, the monthly amount is principal divided by the number of months. TRY 1,000,000 / 6 = TRY 166,666.67. The official table gives the whole-lira rounded figure. Multiplying that rounded payment by six gives TRY 1,000,002; the two-lira difference is not evidence of an extra fee. The precise installment allocation and final payment must be read from the bank’s contractual payment schedule.
A longer term also changes the amount financed
The T10F V2 twelve-month option has a lower installment, but its principal falls to TRY 600,000. Choosing between six and twelve months changes both timing and the buyer’s cash contribution on purchase day. Comparing only interest rates or monthly installments hides that difference. Vehicle version, invoice price, available financing and total payments belong in the same comparison.
TRY 400,000 more upfront on a hypothetical TRY 2 million invoice
Assume a final vehicle invoice of TRY 2,000,000 solely to illustrate the calculation, not as an actual Togg price. A TRY 1,000,000 loan leaves TRY 1,000,000 to pay from the buyer’s own funds; a TRY 600,000 loan leaves TRY 1,400,000. The latter requires TRY 400,000 more upfront. The former has a monthly principal payment approximately TRY 116,666.67 higher. This does not establish approval or availability of both packages for a particular invoice. Insurance and any additional costs are excluded.
Is TRY 100,000 of monthly free cash enough?
Assume a household retains TRY 100,000 each month after essential spending and existing debts. The six-month, one-million-lira option creates a monthly shortfall of about TRY 66,666.67. The eight-month TRY 800,000 option absorbs the entire amount, leaving no margin for unexpected spending. The twelve-month TRY 600,000 option leaves TRY 50,000 in this calculation, but requires a larger initial cash contribution. This arithmetic is not a lending eligibility threshold or a recommendation; income volatility and emergency cash needs differ across households.
COST · Separate zero interest from total cost
Total cash needed to acquire the vehicle comprises the upfront contribution, loan repayments and costs outside those payments. Do not count the principal twice by adding it to both the vehicle price and total installments. Read the bank’s total cost rate, any origination fee and insurance conditions alongside the payment schedule. Charging, maintenance, parking and taxes in later periods also affect the monthly vehicle budget. Since personal cost figures are unavailable, this article does not calculate an all-in financing cost rate.
MY BUDGET · Three payment dates matter together
The initial cash contribution, monthly installments and running costs after the loan ends arise at different times. Having enough savings at the start does not prove strong monthly cash flow; high monthly income does not prove sufficient upfront cash. Treating retained savings as if they will earn guaranteed future returns can obscure this distinction. If another loan becomes necessary to cover installments, the combined burden can differ from the original table.
MY BUSINESS · Fleet terms differ from personal financing
Corporate and sole-trader financing has separate conditions. Financing up to the full invoice amount is not automatically available to personal buyers and remains subject to the bank’s assessment. For a business, regular installments may not align with irregular customer receipts. No tax benefit, expense deduction or investment return is assumed here. A written business loan offer, delivery invoice and collection schedule are needed before deriving a company’s net cost from a personal-customer table.
Calculation notes
Calculations use principal / term and hypothetical invoice − loan. The chart compares packages with different principal amounts; it is not a like-for-like comparison of financing costs. Examples are not price quotations, approval promises or future income forecasts. No exact campaign deadline was given, so none is assumed. Terms at application and the lender’s contractual payment schedule govern the transaction.
 Global economy
 Money and banking
 Money and banking